Practical, age-by-age ways to teach kids about money — from the grocery store to their first paycheck. Real scripts and tactics that actually stick.
- September 16, 2026
AceShowbiz - My seven-year-old once asked me if I could just "go to the machine and get more money." She wasn't being greedy. She genuinely thought the ATM was a magic box that dispensed cash to anyone who remembered their code. That moment changed how I talk about money at home — and it's probably why you're reading this too.
Here's the uncomfortable truth: most kids learn almost nothing about money in school. Only about 20 states require a personal finance course to graduate high school, according to the Council for Economic Education, and even those classes usually land in junior year — long after money habits have taken root. The rest is on us.
The good news is that teaching kids about money doesn't require a spreadsheet, a lecture, or a finance degree. It requires small, repeated moments that fit into your normal day. Let's walk through what actually works, by age and by situation.
Start With Your Own Money Habits (Yes, Really)
Kids absorb far more from what you do than what you say. If you swipe a card without ever mentioning what's happening, your child learns that money is invisible and infinite. If you complain about being broke but then order takeout three nights a week, they learn that money talk is just noise.
You don't need to be perfect. You just need to narrate. Simple phrases like "I'm choosing the cheaper cereal because we're saving for our beach trip" or "This costs more than I want to spend today" do more than any lesson plan. You're showing them that money involves choices, not just availability.
One practical move: pick one money habit you're willing to make visible this month. Maybe it's comparing prices at the store out loud. Maybe it's showing your child the grocery total and saying, "We planned for $150 and spent $162 — so we'll skip the drive-thru this week." That single habit, repeated, builds more financial intuition than a hundred conversations about "the value of a dollar."
Don't Hide All Financial Stress
There's a difference between burdening your kids and pretending money problems don't exist. If you lose your job, you don't need to share the mortgage details with a nine-year-old. But you can say, "We're being extra careful with money right now, so we're pausing our Friday pizza night for a bit."
That kind of honesty teaches resilience. Kids who see adults adjust and cope learn that financial setbacks are survivable — not catastrophic secrets.
Ages 3 to 7: Make Money Concrete
At this age, money is abstract. Coins are toys. Cards are mysterious. Your job is to make money physical and visible, because abstract concepts don't stick yet.
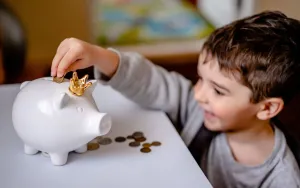
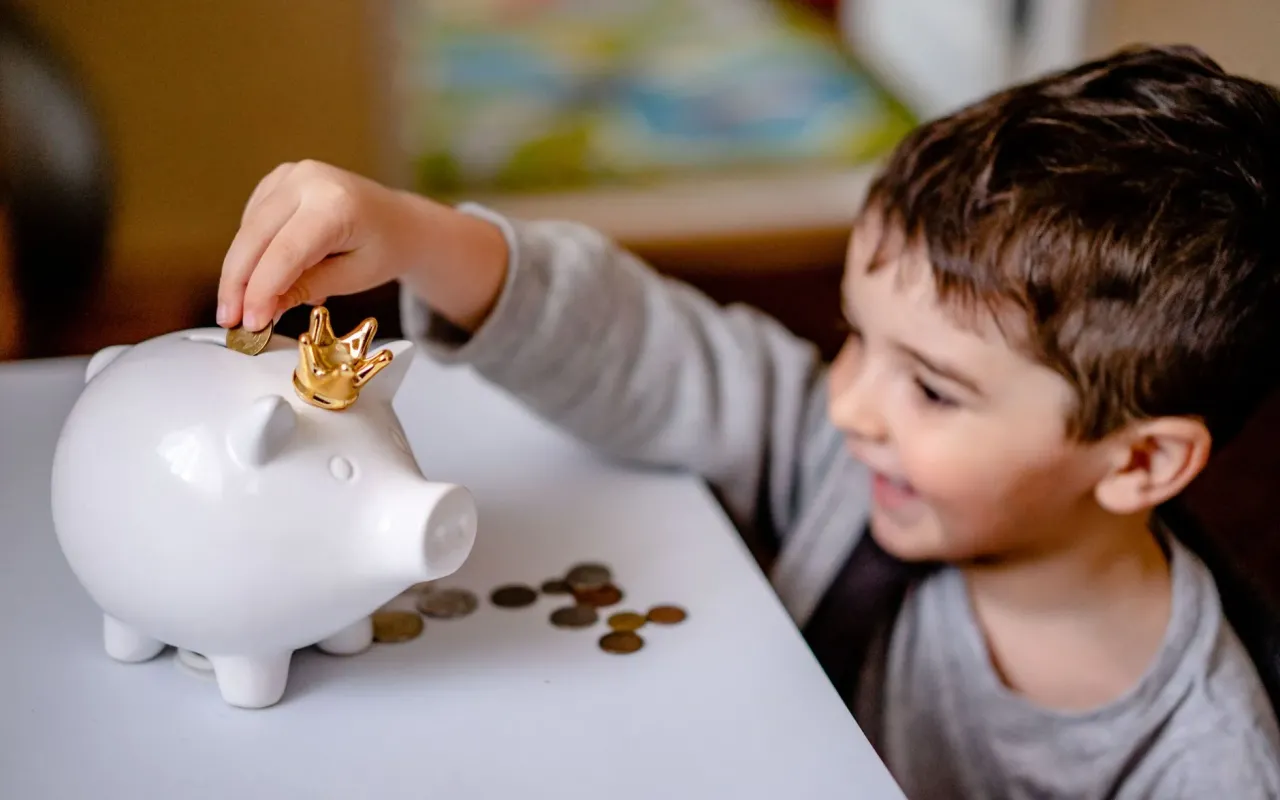
Use a clear jar, not a piggy bank you can't see through. Let your child watch the money pile up. Count it together. When they want a $4 toy, help them count out four dollars from the jar and hand it to the cashier themselves. That physical exchange — money leaves your hand, item comes back — is the single most powerful lesson for this age group.
You can also start naming the three jobs of money: spend, save, give. Even a three-year-old can drop a coin into three different jars. You're not teaching budgeting yet. You're teaching that money has purposes, and that spending everything right away isn't the only option.
A Script That Works
When your child begs for something at the store, try this instead of "no" or "we can't afford it": "That's a great thing to want. Let's take a picture of it and add it to your wish list. If you still want it next week, we'll count your jar money."
You've just taught delayed gratification, goal-setting, and the link between saving and buying — in about fifteen seconds, with zero tears. The wish list trick also kills about 80% of impulse requests, because most of them evaporate by next week.
Ages 8 to 12: Introduce Allowance, Chores, and Real Choices
This is the sweet spot. Kids this age can do math, understand trade-offs, and — crucially — care about having their own money. This is when an allowance becomes a teaching tool instead of just free cash.
There's a long-running debate about whether allowance should be tied to chores. Here's a practical middle ground: pay a base allowance that's unconditional (it's your job as a parent to teach them), and offer optional paid jobs beyond normal household responsibilities. That way, kids learn that some money is a family given and some money is earned through extra effort.
A common starting point is $1 per week per year of age — so a ten-year-old gets $10 weekly. Adjust for your budget. The amount matters less than the system: money arrives on a schedule, and it's theirs to manage.
Let Them Make Bad Purchases
This is the hardest part. When your ten-year-old wants to blow $30 on a cheap toy that will break in a week, every instinct says intervene. Don't.
A $30 mistake at age ten is tuition. A $3,000 mistake at age twenty-five is a crisis. Let them feel the sting of a bad buy now, when the stakes are tiny. Then, instead of saying "I told you so," ask: "What would you do differently next time?" That question turns a regret into a lesson.
Practical tip: set one rule — no borrowing. If they run out of money before allowance day, they wait. No advances, no bailouts. The discomfort of an empty wallet teaches more than any lecture about budgeting ever will.
Ages 13 to 17: Bank Accounts, Budgets, and the First Job
Teenagers are wired for independence, so lean into it. Open a real bank account with a debit card in their name (with you as co-signer if needed). Let them see a balance, make transfers, and — yes — occasionally overdraft. Many banks waive fees for teen accounts, and some offer parental controls you can dial back as trust grows.
This is also the age to introduce a simple budget. Not a spreadsheet with forty categories — three buckets are enough: save, spend, give. If they get a part-time job, help them decide what percentage goes where. A common split is 50% save, 40% spend, 10% give. The exact numbers matter less than the habit of dividing money before spending it.
If your teen is eyeing a big purchase — a car, a laptop, concert tickets — turn it into a project. Have them research prices, calculate how many hours of work it takes to afford it, and set a savings timeline. Suddenly, "I want a $400 phone" becomes "that's 40 hours at my job." That math changes everything.
Talk About Credit Before They Get a Card
Most teens get their first credit card offer the moment they turn eighteen, and many sign without understanding interest. Explain it plainly: a credit card is borrowing money that must be paid back, and if you don't pay in full, the bank charges you extra for the privilege.
Show them a real example. A $1,000 balance at 22% APR, paid with minimum payments, can take years to clear and cost hundreds in interest. That single illustration sticks with teenagers far better than any abstract warning.
Teach the Stuff School Skips: Investing, Taxes, and Scams
By the time kids hit their mid-teens, they're ready for the topics most adults still avoid. You don't need to be an expert — you just need to be honest about what you know and curious about what you don't.
Start with compound interest, because it's the most powerful concept in personal finance and the easiest to demonstrate. Show them that $100 invested at 7% annually becomes roughly $200 in ten years and nearly $400 in twenty — without adding a dollar. Then flip it: the same math works against you with debt. That contrast lands hard.
Taxes are next. When your teen gets their first paycheck and freaks out that the number is smaller than expected, that's a teaching moment, not a complaint session. Walk through the difference between gross pay and net pay, and explain what FICA and withholding actually are. Ten minutes of explanation prevents years of confusion.
Finally, talk about scams. Teenagers are prime targets for fake job offers, crypto schemes, and "you've won a prize" texts. Teach one rule: if someone asks you to pay money to receive money, it's a scam. Period. That rule alone will protect them for life.
Make It a Family Thing
One of the most effective things you can do is make money a normal dinner-table topic. Not stressful, not secret — just normal. Share a money win, a money mistake, or a money question once a week. Kids who grow up hearing adults talk about money calmly become adults who talk about money calmly.
And if you're learning alongside them? Say so. "I didn't learn this until I was thirty, and I want you to know it at fifteen" is a powerful thing for a kid to hear. It signals that financial knowledge isn't innate — it's learned, and they're getting a head start.
The Long Game: Raising Adults, Not Just Savers
The goal isn't to raise a kid who hoards every penny. It's to raise an adult who understands that money is a tool — one that can create freedom, security, and generosity, or one that creates stress and debt, depending on how it's used.
That means letting them practice now, while the stakes are low and the safety net is you. Let them overspend. Let them save for something and change their mind. Let them negotiate their allowance. Every awkward, imperfect money moment is building the muscle they'll need at twenty-five, thirty-five, and beyond.
And here's the part nobody tells you: you'll learn something too. Teaching your kid to pause before buying, to save before spending, to ask "can I afford this?" — those questions have a way of echoing back at you. The best financial education goes both directions.
Start small. Pick one conversation this week. One jar, one wish list, one "let's count it together" moment. You don't need a curriculum. You just need to keep talking, keep practicing, and keep letting them learn by doing — even when doing means watching them buy something dumb. That's not failure. That's the whole point.