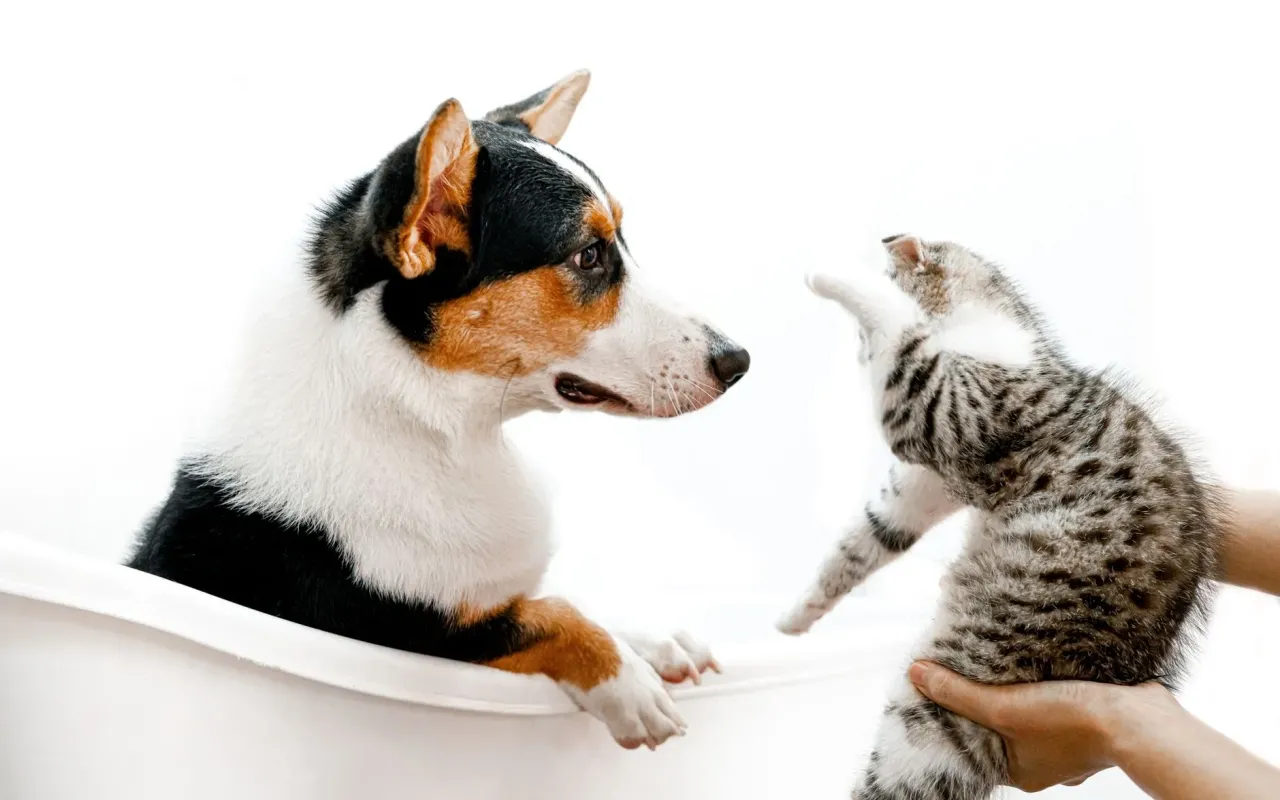
Pet insurance for dogs costs way more than for cats—but the gap isn't the whole story. Here's what you'll actually pay and when it's worth it.
- November 12, 2026
AceShowbiz - Your neighbor's golden retriever just had a $4,200 knee surgery. Your coworker's cat swallowed a hair tie and racked up a $2,800 vet bill. Both of them are now Googling pet insurance at 11 p.m. wondering the same thing: is this actually worth it, and why does the dog cost so much more to insure?
Here's the number that surprises most people: the average monthly premium for a dog is roughly $56, while a cat runs about $32, according to recent industry data from the North American Pet Health Insurance Association. That's a real gap—but it's not the whole story. The type of pet you have, its age, your ZIP code, and how you structure the policy all swing the price by hundreds of dollars a year. Let's break down what you'll actually pay and when the math tips in your favor.
Why Dogs Cost More to Insure Than Cats
The short answer is risk. Dogs get injured more often, eat more things they shouldn't, and rack up bigger bills when things go wrong. A torn ACL in a Labrador can run $3,000 to $5,000 per knee, and large breeds are prone to it. Cats, meanwhile, are cheaper to treat on average because they're smaller, less likely to be hit by cars, and tend to have fewer traumatic injuries.
But the gap isn't just about accidents. Breed matters enormously. Insuring a French bulldog or a Great Dane can cost two to three times what you'd pay for a mixed-breed dog, because those breeds come with known hereditary issues—breathing problems, hip dysplasia, heart conditions. A domestic shorthair cat, by contrast, is about as low-risk as it gets in the pet insurance world.
So what does this mean for you? If you're choosing between insuring a dog and a cat, the cat will almost always be the cheaper policy. But that doesn't mean the dog policy is a bad deal—it's priced higher because the potential payout is higher. The real question is whether your specific animal's risk profile justifies the premium.
Practical tip: Before you buy, ask the insurer for a quote at two or three deductible levels. On a dog policy, bumping your deductible from $250 to $500 often cuts the monthly premium by 20-25%, and that savings can outweigh the higher out-of-pocket cost if your dog stays healthy.
The Real Cost Breakdown: Premiums, Deductibles, and Reimbursement
Monthly premiums are just the entry fee. The true cost of a plan depends on three dials you control: your deductible, your reimbursement rate, and your annual coverage limit. Most plans let you set a deductible between $100 and $1,000, a reimbursement rate of 70%, 80%, or 90%, and an annual limit from $3,000 up to unlimited.
Here's how those dials interact. A dog policy with a $250 deductible, 90% reimbursement, and unlimited annual coverage might run $65 a month. Drop to 70% reimbursement with a $500 deductible and a $5,000 annual cap, and you might pay $38 a month. Over a year, that's a $324 difference in premiums—but if your dog has a $4,000 surgery, the cheaper plan pays out $2,450 while the pricier one pays $3,375. The "cheaper" plan can cost you more in a bad year.
Cats follow the same logic at lower numbers. A cat policy with strong coverage might run $40 a month, while a budget version drops to $22. The trade-off is identical: you're betting on whether your pet will have a major claim.
Practical tip: If you can afford a higher deductible, do it. Most pet owners never hit their deductible in a given year, so paying for a low deductible is often wasted money. Keep the savings in a separate pet emergency fund.
Accident-Only vs. Accident-and-Illness: The Price Gap That Matters
There are two main flavors of pet insurance, and the price difference between them is bigger than the dog-versus-cat gap. Accident-only plans cover things like broken bones, bite wounds, and swallowed objects. Accident-and-illness plans add coverage for cancer, diabetes, infections, allergies, and other diseases.
For dogs, accident-only coverage averages around $20 a month, while accident-and-illness runs closer to $56. For cats, it's roughly $12 versus $32. That means a cat with full illness coverage can cost less than a dog with accident-only coverage—a fact that trips up a lot of shoppers comparing quotes across species.
Which should you pick? Accident-only plans are cheap but leave you exposed to the most expensive category of claims: chronic illness and cancer treatment, which can easily run $5,000 to $10,000. If your budget only stretches to accident-only, that's better than nothing—but understand you're covered for the less common scenario, not the more common one.
Practical tip: If you're torn, price out accident-and-illness with a higher deductible rather than dropping to accident-only. You'll often land near the same monthly cost while keeping illness protection intact.
How Age, Breed, and Location Move the Number
Two people can insure identical golden retrievers and pay wildly different premiums. Age is the biggest lever: premiums typically rise 30-50% as a pet moves from puppy or kitten stage into adulthood, and climb again into senior years. Insurers know older pets file more claims, and they price accordingly.
Location matters too. Vet costs vary significantly by region—a procedure in San Francisco can cost 40% more than the same procedure in rural Ohio—and insurers adjust premiums to match local pricing. Breed is the third big factor, especially for dogs with known hereditary conditions. Mixed-breed dogs and cats often get the best rates because they carry fewer predictable genetic risks.
This is why comparing quotes from friends or online averages only gets you so far. Your actual number depends on your specific pet and address. Get personalized quotes from at least three insurers before you decide anything.
Practical tip: Enroll your pet young. Insurers can't reject you for pre-existing conditions you disclose at signup, but they also won't cover them—and once a condition is on your pet's record, it's excluded forever. Locking in coverage before problems appear is the single biggest cost-saving move in pet insurance.
When Pet Insurance Actually Pays Off (and When It Doesn't)
Let's do the honest math. If you pay $56 a month for dog insurance, that's $672 a year. Over a 10-year lifespan, you've spent roughly $6,700—more if premiums rise with age. For that to pay off, your dog needs to generate claims that exceed what you paid in, after deductibles and reimbursement limits. Many dogs never do. Some do spectacularly.
The people who come out ahead are usually those who face a single catastrophic event—a cancer diagnosis, a major surgery, a chronic condition requiring lifelong medication. Those bills routinely hit five figures, and a good policy turns a financial crisis into a manageable copay. The people who lose are those who pay premiums for years and file small claims that barely clear the deductible.
So the decision isn't really about averages—it's about your risk tolerance and your savings buffer. If you have $10,000 sitting in an emergency fund you're willing to spend on your pet, self-insuring is a legitimate strategy. If a $5,000 vet bill would mean a credit card or a GoFundMe, insurance is buying peace of mind at a fair price.
Practical tip: Run the break-even math yourself. Multiply your monthly premium by 12, then by your pet's expected lifespan. Compare that to the cost of one major surgery in your area. If the surgery number is close to or higher than your lifetime premiums, the policy is worth serious consideration.
Smart Ways to Lower Your Premium Without Gutting Coverage
You don't have to accept the first quote. There are several legitimate levers to pull. First, shop multiple insurers—premiums for identical coverage can vary by 40% or more between companies. Second, ask about multi-pet discounts, which typically save 5-10% per additional pet and can make insuring both your dog and cat cheaper than insuring the dog alone at a competitor.
Third, consider a higher deductible as discussed, and pair it with a dedicated savings account for the difference. Fourth, check whether your employer, credit union, or a professional association offers a pet insurance discount—many do through group programs. Finally, keep your pet at a healthy weight and up to date on preventive care; some insurers now offer wellness rewards or premium credits for documented preventive care.
What you shouldn't do is skip coverage on a young pet to save money now. Pre-existing conditions are the silent budget killer in pet insurance—once your pet develops one, it's excluded for life, and you'll wish you'd enrolled earlier. The cheapest policy is the one you buy before anything goes wrong.
Practical tip: Get quotes from at least three insurers on the same day, using identical deductible and reimbursement settings, so you're comparing apples to apples. Then check each insurer's claim-processing reputation before you commit—a cheap premium from a company that fights every claim isn't a bargain.
The bottom line: cats are cheaper to insure than dogs, accident-only is cheaper than full illness coverage, and young pets are cheaper than old ones. But the smartest move isn't chasing the lowest premium—it's matching your coverage to your actual financial risk and enrolling before your pet's health history locks you out of the best options.